Electric Car Mileage Tax Due to Start on 1st April 2028:
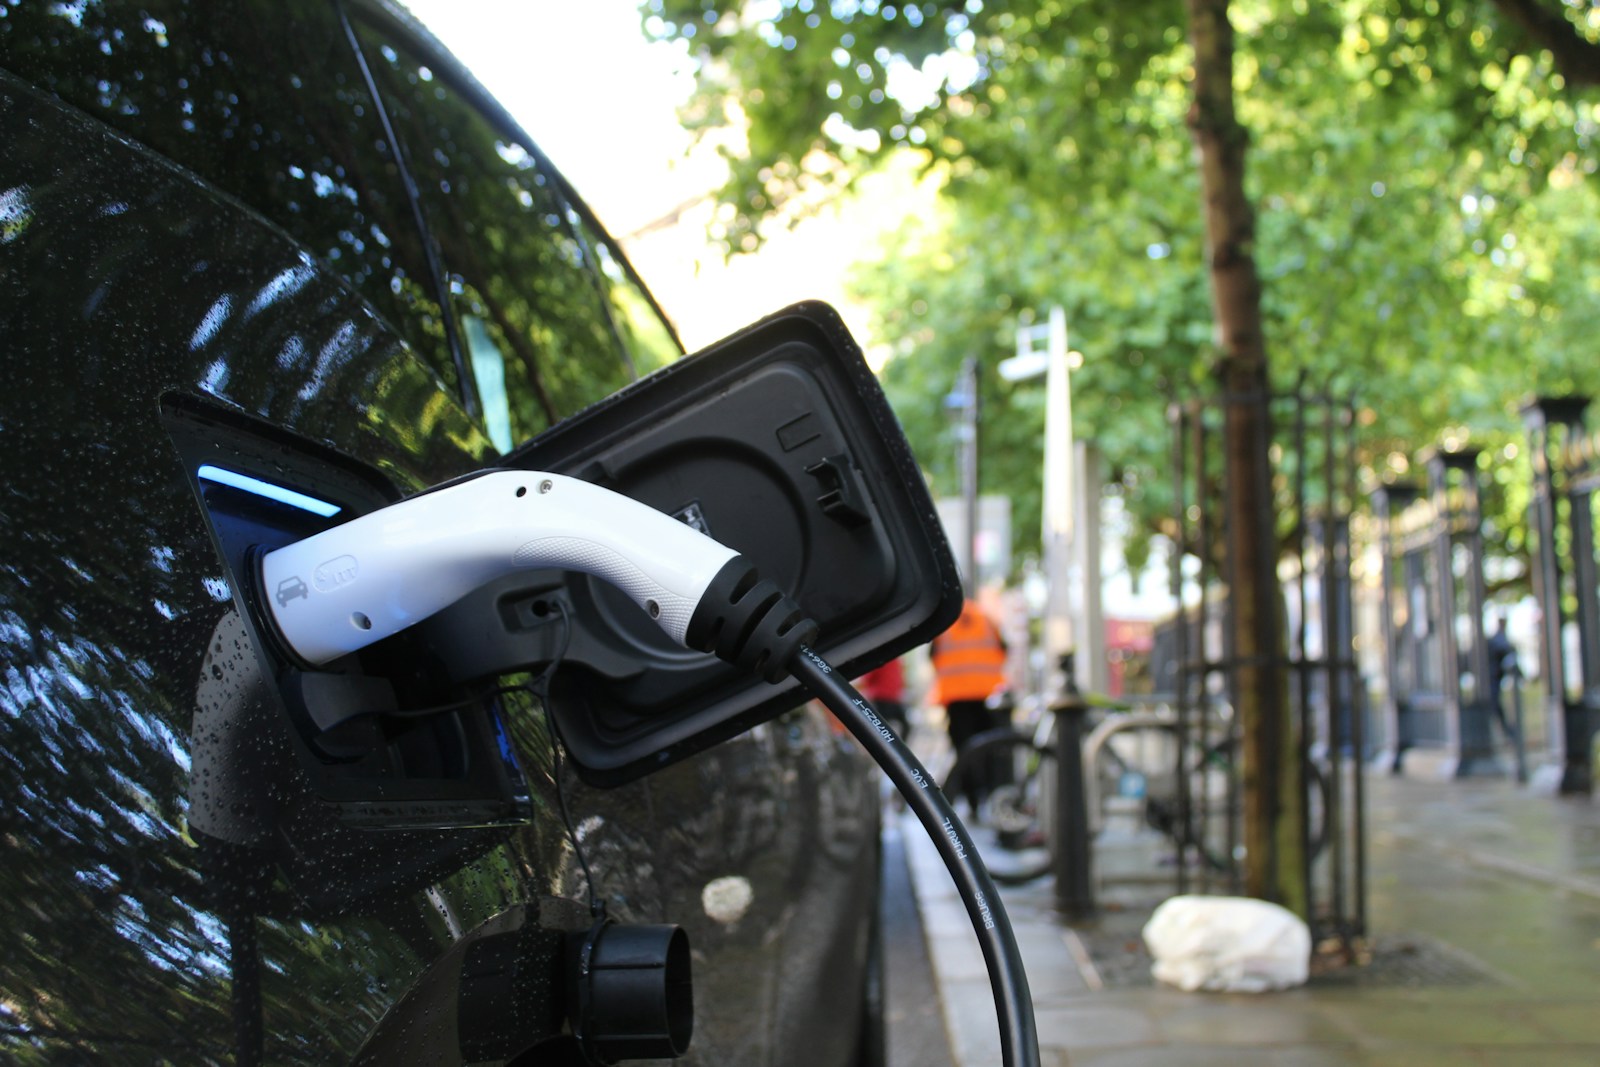
The Government plans to introduce Electric Vehicle Excise Duty (eVED), a mileage-based charge for eligible electric cars, from 1st April 2028.
The announced initial rate is 3p per mile for fully electric cars and hydrogen fuel-cell cars, and 1.5p per mile for plug-in hybrids. The charge is intended to sit alongside existing vehicle tax, not replace it. Some legislative and implementation steps remain outstanding, so drivers should treat the figures below as estimates based on the announced policy, rather than a final individual bill.
Change at a glance
CHANGE: A mileage-based Electric Vehicle Excise Duty (eVED) is planned for eligible cars.
WHEN: 1st April 2028, according to HMRC’s published policy paper.
WHERE: UK-wide, including Northern Ireland, subject to the stated scope of the policy.
WHO IT AFFECTS: Registered keepers of eligible fully electric, plug-in hybrid and hydrogen fuel-cell cars.
ANNOUNCED RATES: 3p per mile for fully electric and hydrogen fuel-cell cars; 1.5p per mile for plug-in hybrids.
WHAT TO DO NOW: No immediate mileage-tax payment is due under the announced start date. Check official guidance as implementation details are confirmed.
LAST CHECKED: 14th October 2026.
What is Electric Vehicle Excise Duty?
Electric Vehicle Excise Duty, or eVED, is a new charge based on how far an eligible car is driven. HM Revenue & Customs says it is intended to extend the existing Vehicle Excise Duty (VED) system. VED is commonly known as vehicle tax or road tax.
The Government says the mileage charge is intended to help address the difference between electric-car drivers and petrol or diesel drivers, who pay fuel duty when they buy fuel. eVED is designed so that the amount charged varies with mileage, rather than being the same for every driver regardless of how far they travel.
The Government has confirmed the policy and its intended start date, and published a consultation response setting out the refined design. However, its July 2026 response says the next phase will finalise legislation, build the supporting DVLA systems and publish guidance. The exact operational details should therefore be distinguished from the announced policy.
When does the electric car mileage tax start?
HMRC’s policy paper states that eVED will take effect from 1st April 2028. The announced date is therefore the date to use when planning for the change, while keeping in mind that legislation and operational arrangements must be completed.
The charge is intended to be collected through the existing vehicle-tax arrangements administered by the Driver and Vehicle Licensing Agency (DVLA). It is not accurate to assume that every driver will receive a separate bill on 1st April itself. The policy describes eVED being renewed alongside VED, from the vehicle’s next vehicle-tax renewal from the commencement date.
Which vehicles are affected?
The July 2026 consultation response confirms the following categories are within the planned scope at introduction:
- Fully electric cars: battery-electric cars, charged at 3p per mile.
- Plug-in hybrid cars: cars that can be charged externally and also use petrol or another fuel, charged at 1.5p per mile.
- Hydrogen fuel-cell cars: confirmed at the 3p-per-mile electric-vehicle rate.
- Range-extender electric cars: confirmed at the 1.5p-per-mile plug-in hybrid rate.
The scope is based on UK-registered cars, including Northern Ireland. M1 special-purpose vehicles (M1SP), such as hearses and campervans, are excluded at introduction, as are vans, buses, coaches and heavy goods vehicles. Cars with internal-combustion engines that have been converted to electric are also out of scope at introduction.
How much will drivers pay per mile?
The announced initial rates are 3p per mile for fully electric cars and hydrogen fuel-cell cars, and 1.5p per mile for plug-in hybrid cars. These are the policy’s announced starting rates, not a promise that the same figures will apply indefinitely.
Announced initial eVED rates
Fully electric car
3p
per mile
Plug-in hybrid
1.5p
per mile
Hydrogen fuel-cell car
3p
per mile
The initial rates are not fixed forever. The Government says they will be uprated in 2029 to 2030 and in later years in line with Consumer Prices Index (CPI) inflation. If a driver needs to top up mileage after the rate has changed, the top-up will use the rate then in force.
What could the charge cost at different mileages?
The examples below show the annual charge if the announced initial rates are applied to the mileage shown. They are illustrations, not individual bills. The final amount will depend on the rules for estimating mileage and reconciling it against the actual mileage recorded.
Estimated annual charge at the announced rates
| Annual mileage | Fully electric (3p per mile) |
Plug-in hybrid (1.5p per mile) |
|---|---|---|
| 5,000 miles | £150 | £75 |
| 8,000 miles | £240 | £120 |
| 12,000 miles | £360 | £180 |
Illustrative calculations using announced initial rates. These figures exclude existing VED, fuel or charging costs, insurance, servicing and other vehicle expenses.
For example, 8,000 miles multiplied by £0.03 gives £240 for a fully electric car. At the plug-in hybrid rate, 8,000 miles multiplied by £0.015 gives £120. At the same mileage, a hydrogen fuel-cell car would also produce an illustrative £240 charge if the announced 3p rate applies.
The calculation is based on miles driven, so annual mileage matters. A driver covering 5,000 miles would have a lower illustrative eVED charge than someone covering 12,000 miles in the same vehicle category. For more on motoring costs, see our guide to using fuel prices in Google Maps; it is a separate tool and does not calculate eVED.
How will drivers report mileage and pay?
HMRC’s policy paper and July 2026 consultation response describe a system in which drivers provide an odometer reading and estimate the mileage they expect to cover during the forthcoming vehicle-tax period, typically a year. This estimate is used to calculate the initial charge. For cars under three years old (under four years old in Northern Ireland), the Government has decided not to proceed with separate routine mileage checks before the first MOT. Keepers will provide an odometer reading and estimate their mileage at each vehicle-tax renewal. The Government says verified mileage from the first MOT can be used to reconcile the keeper’s readings and estimate.
How the proposed process is intended to work
At vehicle-tax renewal, provide the car’s odometer reading. The Government has dropped separate routine pre-MOT mileage checks for cars under three years old, or under four years old in Northern Ireland.
Estimate how many miles the car is expected to travel during the next vehicle-tax period, typically a year.
The published proposal allows monthly, six-monthly or annual payment through existing vehicle-tax payment channels. The draft legislation published alongside the response proposes an eVED surcharge of 5% where a 12-month vehicle licence is paid by instalments. For a six-month licence, it proposes a 10% surcharge, reduced to 5% if paid by direct debit. These are draft provisions and may change before implementation. Check the final payment guidance when the scheme is introduced, as the operational arrangements are still being developed. Drivers expecting to exceed their estimate can top up at the rate then in force.
Verified MOT mileage is intended to be compared with the estimate. Underpayments can trigger a balancing payment; unused mileage is generally carried forward as credit, with cash refunds limited to specified cases.
eVED is intended to use the existing vehicle-tax payment channels. The July 2026 consultation response says motorists will be able to pay monthly, every six months or annually, using the same channels available for VED, including the DVLA online service or the Post Office. Drivers expecting to exceed their original mileage estimate will be able to top up their mileage balance during the year at the rate then in force. At the relevant reconciliation point, the mileage estimate will be compared with the available mileage reading, using verified MOT mileage where available. If a driver has paid for more miles than they used, the unused mileage credit will ordinarily be carried forward to the next licensing period. The July 2026 consultation response also proposes cash refunds in limited circumstances, including some unexpected changes in financial circumstances. The final rules and process should be checked against official guidance when published.
Some practical details still depend on legislation and regulations. Do not assume the exact screens, deadlines, adjustment rules or every step of the collection process are final until the Government publishes the relevant implementation guidance.
The policy paper says mileage data is already collected at annual MOT tests and is available to view for most cars on GOV.UK. It does not mean drivers should assume no mileage reading will be requested for eVED; the published approach specifically refers to odometer readings as part of the process.
Does eVED replace existing vehicle tax?
No. The policy is designed as an extension of existing Vehicle Excise Duty, with the mileage-based charge added alongside VED for eligible cars. Drivers should not assume that paying eVED means they no longer owe ordinary vehicle tax.
The published policy says the eVED charge will be administered by DVLA and will be linked to vehicle-tax renewal. The precise arrangements should be checked against the latest official guidance as the start date approaches.
How does eVED affect the cost of owning an electric car?
The mileage charge is one part of a vehicle’s running costs, not a complete comparison between electric, petrol, diesel and hybrid cars. The illustrative eVED amount will vary with annual mileage, but people comparing vehicles should also consider existing VED, the cost of electricity or fuel, insurance, servicing, purchase price and how they use the car.
Plug-in hybrids have a lower announced eVED rate than fully electric cars. The Government’s consultation response explains that plug-in hybrids can use petrol as well as electricity and will continue to pay fuel duty on petrol used. The reduced rate is intended to recognise that difference without requiring drivers to report how many miles they travelled in each mode.
That does not establish that one type of car will always be cheaper overall. The result will depend on the vehicle, the driver’s mileage and energy costs, and the final rules applying when eVED begins.
What happens next?
HMRC’s policy paper sets out 1st April 2028 as the date the measure is intended to take effect. It also describes draft legislation and further regulations needed for the system to operate. The policy has been announced, but readers should distinguish that policy position from the detailed legal and administrative provisions that are still to be completed.
Drivers do not need to calculate or pay an eVED charge immediately on the basis of this article. Before the scheme begins, check the latest GOV.UK guidance for the rules that apply to your vehicle and the steps DVLA asks you to follow.
Set out in published policy
- Intended start date of 1st April 2028.
- Initial rates of 3p and 1.5p per mile for the stated vehicle categories.
- Charge intended to sit alongside VED.
- Odometer readings and estimated annual mileage form part of the proposed system.
Still check before the start date
- Final legislation and regulations bringing the measure into operation.
- The complete operational instructions for drivers.
- The final practical details of mileage reconciliation and payment administration.
- Any updates published by HMRC or DVLA after this article was checked.
Information checked
This article was checked against official Government material available on 14th October 2026. The commencement date and initial rates are set out in HMRC’s policy paper; the July 2026 consultation response provides the updated design details on vehicle scope, payment options and mileage verification:
- HMRC: Draft eVED legislation (accessible version).
- HMRC: eVED consultation response.
- GOV.UK: Vehicle tax for electric and low-emission vehicles.
This article provides general consumer information based on official sources available when checked. The policy and implementation details may change. Consult current GOV.UK guidance for the latest position before making decisions about your vehicle.